What is liquidity — and why it matters which shares you pick
Some shares can be bought or sold in seconds. Others take much longer — and if you need to sell in a hurry, the delay can cost you. That difference has a name: liquidity. Here is what it means and why it matters.
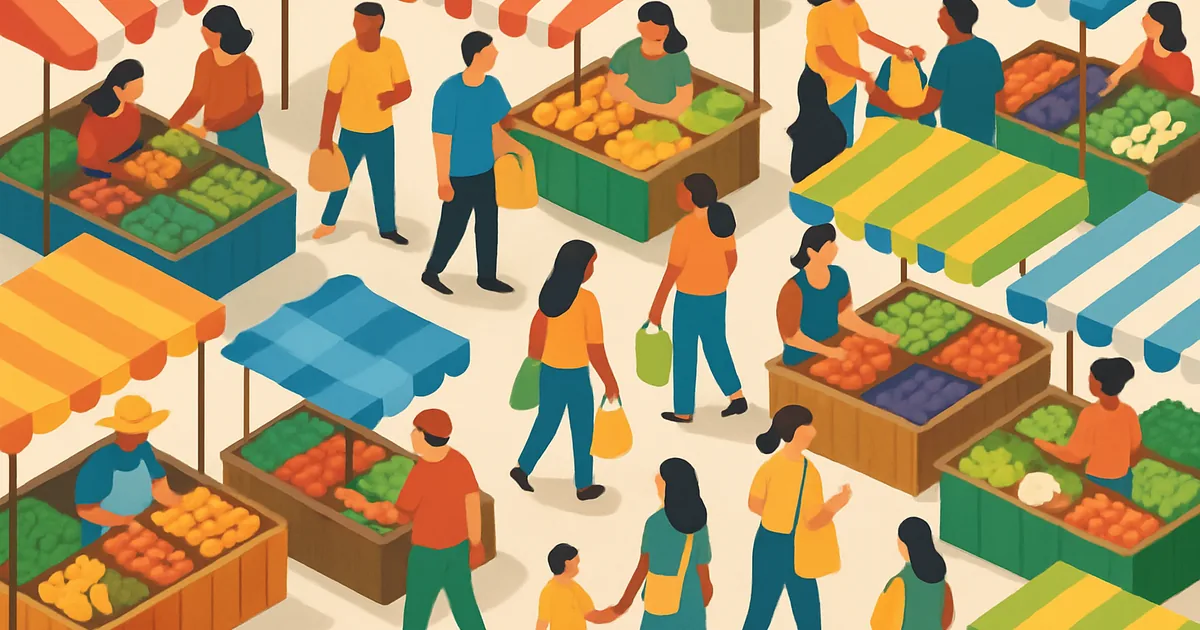
Imagine you are selling something at an open-air market on a busy Saturday. Hundreds of shoppers are walking past, most of them carrying cash, and within minutes you have found a buyer at a fair price. Now imagine trying to sell the same item from a tiny stall tucked in an alley that almost nobody visits. Even if your price is perfectly reasonable, you might wait all day. The item has not changed. The market around it has. That contrast — between a busy, active market and a thin, quiet one — is exactly what investors mean when they talk about liquidity.
What liquidity actually means
In investing, liquidity describes how quickly and easily you can convert an asset into cash at a fair price. The two words matter equally. A fire-sale is not truly liquid: yes, you can sell anything if you drop the price far enough, but if you have to accept 60p on the pound to find a buyer, that is not a fair exit. True liquidity means a ready market at or near the quoted price — right now, not next week.
Think of the spectrum like this:
- Most liquid: physical cash itself; then instant-access savings accounts; then large-cap shares in the FTSE 100, where millions of pounds change hands every minute.
- Moderately liquid: FTSE 250 companies, government bonds, ETFs — still tradeable within seconds, but with a slightly wider bid-ask spread.
- Illiquid: property (takes weeks to find a buyer), private company stakes (no public market at all), fine art, antiques.
Along the swamp-to-river spectrum, a liquid asset is the river: water flowing freely in and out. An illiquid one is the swamp: money gets stuck and is hard to move without disturbing the whole ecosystem.
Why some shares are far more liquid than others
Trading volume and company size
The biggest driver of share liquidity is simply how many people are trading it at any given moment. A large blue-chip company — think a major high-street bank or a household retailer — has millions of shareholders worldwide. At any second, some want to buy more and others want to sell. That constant, two-way activity creates a deep order book: lots of buyers at prices just below the current quote, lots of sellers just above. The result is that your own trade disappears into the flow like a raindrop into a river — it barely moves the price.
A small or micro-cap company is completely different. Fewer investors follow it; fewer shares change hands each day. A single large order can shift the price noticeably, and if you want to sell at an awkward moment, you might find yourself waiting for a buyer to appear. To understand why size matters so much in the first place, our guide to market capitalisation explains how a company's total market value shapes its place in the investment world.
The bid-ask spread as a liquidity signal
You can gauge liquidity at a glance by looking at the bid-ask spread. The bid price is the highest price a buyer is willing to pay right now. The ask price (sometimes called the offer) is the lowest a seller will accept. The spread is the gap between them.
In a highly liquid market — say, a FTSE 100 share priced at £10.00 — the spread might be just 1p or 2p. In an illiquid one it could be 20p, 50p or more. That gap is effectively the hidden cost of trading: the moment you buy at the ask and immediately want to sell at the bid, you are already down by the spread. No formula is needed to understand the principle: a wider gap means fewer people want to trade, and the market maker handling the deal needs a bigger cushion to compensate for the risk of being stuck with the position.
Why liquidity matters in the Student Investor Challenge
In your virtual £100,000 portfolio, the Challenge focuses on top-listed shares — predominantly FTSE 100 and FTSE 250 companies. These are among the most liquid markets in the UK. In practice, that means you can usually buy and sell at almost exactly the price shown on screen, with no delay and a tiny spread. It feels instant because it nearly is.
But the Challenge teaches you something important even so. Because you are working with well-established companies, you can observe how a large-cap blue chip behaves compared to a more speculative holding. You will notice that the big names tend to have steadier, tighter price movements, while smaller companies in the index can occasionally gap up or down sharply on low volume. That difference is liquidity at work.
In the real world, a fund manager running billions of pounds cares deeply about liquidity. If they need to sell a large position in an illiquid stock, each tranche of the sale pushes the price down further, meaning later tranches fetch less than earlier ones. This is called market impact, and it is one reason professional investors track market depth so carefully. Your Challenge portfolio is too small to experience market impact on FTSE-listed shares, but the concept is exactly the same.
The liquidity trade-off
Illiquid assets are not automatically bad investments. In fact, they often offer higher potential returns precisely because they are inconvenient. Property is the classic example: over long periods, house prices in many areas have outpaced the stock market, but you cannot sell a bedroom in an afternoon if you suddenly need the cash. Investors demand a liquidity premium — extra return — to compensate for giving up the flexibility a liquid asset provides.
Exchange-traded funds (ETFs) add an interesting wrinkle here. An ETF can be highly liquid even when its underlying holdings are not. Some bond ETFs trade freely on exchange all day, even though the individual bonds inside them change hands infrequently. If you want to understand how that works and why ETFs have become so popular, our piece on what exchange-traded funds are covers the mechanics in plain English.
The key lesson is that liquidity is a feature you sometimes choose to give up, in exchange for higher expected returns or other advantages — it is a trade-off, not a flaw to fix. For an overview of why UK investors sometimes hold illiquid assets like property or private equity alongside shares, the MoneyHelper website (backed by the UK government) has accessible plain-English guides to different asset classes.
Liquidity and panic selling
One of the most important moments to understand liquidity is during a market sell-off. When investors panic and rush for the exits all at once, liquidity can dry up temporarily: spreads widen, fewer buyers appear, and prices can gap down sharply in a short time. This is not because the underlying businesses have suddenly become worthless. It is because the balance of buyers and sellers has tilted violently to one side, and the market needs time to rebalance.
For the shares in the Challenge — large, well-known FTSE companies — this effect is limited and usually brief. Even in a bad week, you can generally still exit a position at a reasonable price, because the market for these stocks never truly empties of buyers. That is the value of blue-chip liquidity: it protects you from being completely trapped even when sentiment turns ugly.
An illiquid asset in a crisis is a very different matter. Try selling a buy-to-let flat during a housing downturn, or a stake in a private company when sentiment in that sector has curdled, and you may find that no buyer appears at any reasonable price for months. You are trapped — not because the asset is worthless, but because the market for it has evaporated. For more on how prices react to waves of fear and optimism in liquid markets, our volatility guide explains the price-swing connection in detail.
FAQ
What does it mean for a share to be liquid?
A liquid share is one you can buy or sell quickly at a price close to what you see quoted, because there are many buyers and sellers active in the market at any moment. Blue-chip shares in the FTSE 100 are typically very liquid: a deal can be struck in a fraction of a second. An illiquid share might take much longer to trade at a fair price, because fewer people want to deal in it.
Are bigger company shares always more liquid?
Generally yes, but not automatically. Large, well-known companies attract many investors, which creates the steady flow of buyers and sellers that makes a market liquid. Smaller companies have fewer shareholders and lower trading volumes, so their markets can be thin — with wider bid-ask spreads and orders that take longer to fill. There are exceptions: a very newsworthy small company can briefly see a surge in activity, but that frenzy rarely lasts.
Does liquidity affect the price I actually pay?
Yes, through the bid-ask spread. The bid is the highest price a buyer will pay; the ask is the lowest a seller will accept. The gap between them is effectively the cost of trading. In a liquid market the spread might be just a penny or two on a £10 share. In an illiquid one it could be many pence or even pounds, meaning you are already down by that gap the moment you buy. It is not a fee in the traditional sense, but it is very real.
Should I worry about liquidity when using the Challenge?
Not in practice. The Student Investor Challenge lets you trade top listed shares, which are among the most liquid in the UK market. You can buy and sell at near the displayed price without worrying about your order moving the market. What the Challenge does teach you is why those shares behave differently from smaller companies — and that understanding will serve you well if you ever look beyond the FTSE 100 later on.
See it in action
Practise buying and selling the UK’s most liquid shares with a virtual £100,000 — no real money required.
See how it works