What is a profit margin — and what it reveals about a company
Two companies both report £10 million in sales. One keeps £2 million; the other keeps £200,000. The profit margin is the number that explains why — and it is one of the most useful filters you can apply in the Student Investor Challenge.
From revenue to profit — what gets in the way
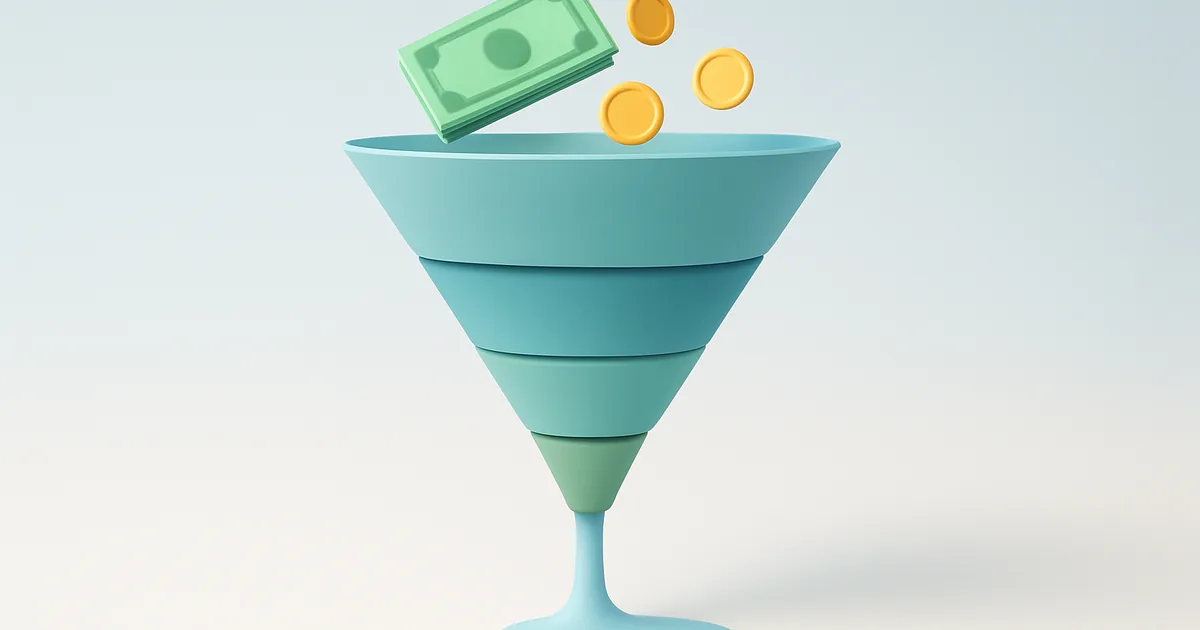
Revenue is the starting point — read our guide if you need a refresher. It is the total of everything a company earns from customers before a single cost is subtracted. But between that raw sales figure and the money a company actually keeps, several layers of expense eat into the total.
First, the direct cost of making or sourcing what was sold: the ingredients, components, or wholesale stock. Next come the overheads of running the business: staff wages, rent, utilities, marketing, and research and development. Finally, interest on any borrowings and the corporation tax bill take their share.
Because these costs arrive in distinct layers, companies report three different profit figures — one for each stage of that journey. A profit margin turns each of those figures into a percentage of revenue, which makes it possible to compare companies of very different sizes, and to track whether a business is becoming more or less efficient over time.
The three types of profit margin
Gross profit margin
Gross profit margin strips out only the direct cost of production — the cost of goods sold, or COGS. The formula is:
Gross profit margin = (Revenue − Cost of goods sold) ÷ Revenue × 100
A simple example: imagine a baker who sells a loaf for £3 and spends £1 on flour, yeast, and energy to make it. The gross margin on that loaf is (3−1)÷3×100 = 67%. That looks impressive — but it says nothing yet about whether the bakery is actually profitable after rent, staff wages, and the lease on the oven.
Gross margins vary enormously by sector. Supermarkets typically run at 3–5%, because they buy and sell at razor-thin mark-ups on huge volumes. Luxury goods companies and software businesses often sit at 60–70% or higher, because the cost of producing one more unit is very low relative to the price it commands.
Operating profit margin
Operating profit margin deducts the overhead costs of running the business on top of COGS. The formula is:
Operating profit margin = Operating profit ÷ Revenue × 100
The gap between gross and operating margin tells you the overhead burden. A company with a 60% gross margin but a 10% operating margin is spending 50 pence in every pound of revenue on wages, rent, marketing, and similar running costs. Whether that is sustainable depends on whether the business can grow revenue faster than those fixed costs rise.
Analysts value the operating margin because it reflects how well management runs the core business day-to-day — before the company’s financing choices (how much debt it carries) muddy the picture.
Net profit margin
Net profit margin is the full bottom-line figure: revenue minus every cost, including interest payments on debt and the corporation tax bill. The formula is:
Net profit margin = Net profit ÷ Revenue × 100
This is the margin investors cite most often, and it feeds directly into earnings per share (EPS) — the figure that drives share-price movements more than almost any other single number.
Net margin shows you what is left for shareholders after the whole machine has been paid for. A company with a 30% gross margin but a 3% net margin is carrying heavy debt, a high tax rate, or both. That is not automatically bad, but it does mean most of the gross profit is committed before it reaches investors.
How to read a margin — and compare companies
The most important rule about margins: they only make sense in context. Comparing a supermarket’s 2% net margin with a pharmaceutical company’s 25% net margin tells you almost nothing useful. Grocery retail and pharmaceuticals are structurally different businesses. The right comparison is either the same company over time, or sector peers.
Consider two fictional FTSE companies in the same sector, both reporting £500 million in revenue:
- Company A: net profit £75 million → net margin 15%
- Company B: net profit £20 million → net margin 4%
Same revenue, very different quality of earnings. Company A retains far more of every pound of sales. If both are growing at similar rates, Company A is likely the stronger business — and probably commands a higher valuation. As our guide on the price-to-earnings ratio explains, a high P/E only looks justified if margins support the profitability behind it.
A falling margin can matter more than the absolute level. A company whose net margin drops from 12% to 9% over two years is worth investigating: something is squeezing profitability, even if the headline numbers still look respectable.
Why margins change — and what that teaches investors
Margins are not fixed. They respond to events inside and outside the business. Understanding what compresses or expands a margin is one of the most transferable skills in investing.
Here are five events that commonly squeeze margins:
- Commodity price spikes — a restaurant chain whose raw ingredient costs surge will see gross margin fall unless it raises menu prices.
- Currency moves — a UK company that buys in US dollars and sells in pounds sees its COGS rise when sterling weakens, compressing gross margin.
- Loss of pricing power — if competitors undercut you, you may have to cut prices to keep volume. Same cost, lower revenue per unit: margin falls.
- New regulation — compliance requirements can add significant overhead, squeezing operating margin.
- Debt taken on — a company that refinances at a higher interest rate, or takes on new borrowings to fund an acquisition, will see net margin shrink even if trading is strong. You can read about this balance-sheet dimension in our guide to what a balance sheet is.
Expanding margins, by contrast, often signal that a business is scaling efficiently: fixed costs (rent, head-office staff, software infrastructure) are growing more slowly than revenue, so each extra pound of sales drops more to the bottom line. This “operating leverage” is one reason investors pay a premium for companies whose margins are consistently improving.
Using margins in the Student Investor Challenge
When a company in your virtual portfolio announces results, margin analysis is one of the quickest ways to decide whether the numbers are actually good or just superficially impressive.
Here is where to find the figures: look in the results press release (RNS on the London Stock Exchange website, or via a financial data site such as London Stock Exchange company profiles). Search for the words “gross margin”, “operating margin”, or “EBITDA margin”. They are usually in the financial highlights section near the top, or in the chief executive’s commentary.
Two quick filters to apply straight away:
- Is the net margin positive? A company losing money at the net level needs a very convincing story about when it will turn profitable.
- Is it trending up or down versus last year? A margin moving in the right direction is a more encouraging signal than a high but falling margin.
One pattern to watch out for in the Challenge: revenue rising while net margin shrinks. This can look positive at first glance — sales are growing! — but it often means the company is buying growth at the expense of profitability. Sustained margin compression tends to disappoint investors eventually.
For a fuller picture, pair margin analysis with EPS: pair margin with EPS for a fuller picture of whether earnings growth is genuinely improving. And you can apply these checks to any of the companies in your virtual portfolio — see how the Challenge portfolio works for a walkthrough of how to find and buy shares in the game.
For further context on how to read UK company filings, Xero’s breakdown of gross vs net profit is a clear, jargon-free reference that complements what you will find in a real results announcement.
Frequently asked questions
What is a good profit margin?
It depends on the sector. A 20% or higher net margin is excellent for most businesses, but a 2% margin is entirely normal in grocery retail. Always compare within an industry rather than using a single universal benchmark — a margin that looks thin in one sector can represent a highly efficient business in another.
What is the difference between gross and net profit margin?
Gross margin only removes the direct cost of producing or buying what was sold. Net margin removes every cost — including running the business, paying interest on loans, and paying tax. Net margin is the figure shareholders ultimately care about most, because it determines what is available for dividends or reinvestment.
Can a company have a high gross margin but still lose money?
Yes. High overhead costs, heavy debt, or large tax bills can wipe out a strong gross margin and leave a company with a thin — or even negative — net margin. A business can be very efficient at making its product but still struggle with the costs of running the wider organisation, paying interest on borrowings, or meeting its tax obligations.
How do I find profit margins for a company I am researching?
Look in the company’s results announcement — known as an RNS on the London Stock Exchange website — or on a financial data site such as Morningstar or the London Stock Exchange’s company profiles. The figures you want are gross profit, operating profit, and net profit, each divided by revenue. Most results announcements include the margin percentages directly in the headline summary, alongside the year-on-year comparison.
Put it into practice
Apply these concepts with a virtual £100,000 portfolio — no real money, real companies, real results announcements.
See how it works