What compounding is, and why it rewards patience
It has been called the most powerful force in finance, yet the idea behind it is simple enough to explain in a sentence. Once it clicks, a lot of grown-up money advice suddenly makes sense.
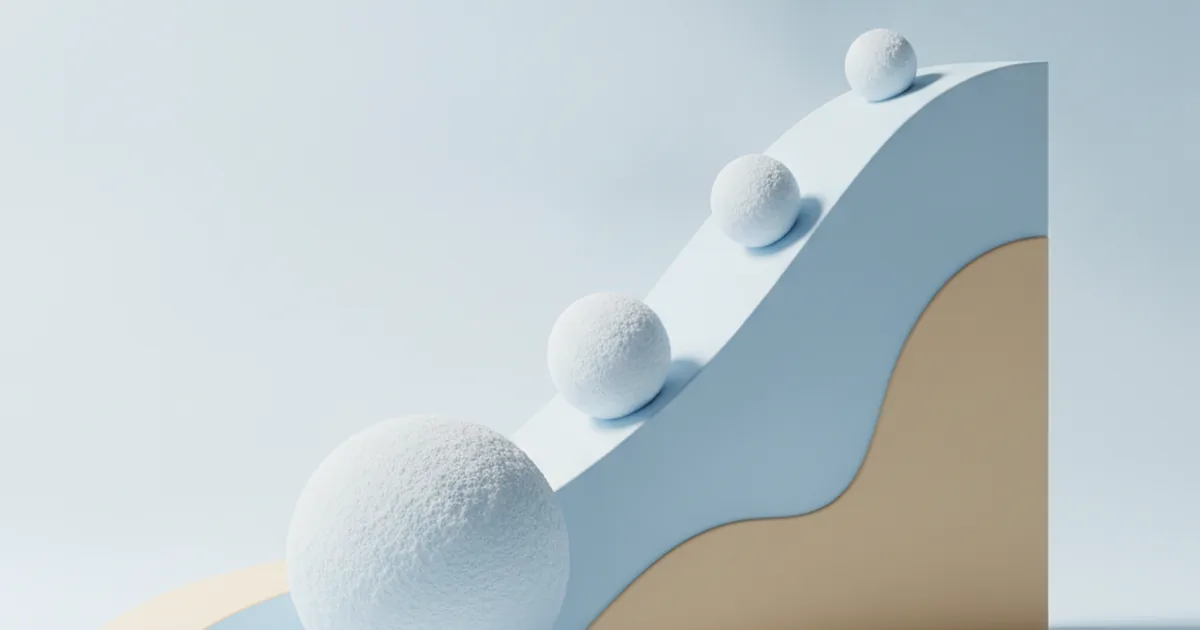
Picture a snowball at the top of a long, snowy hill. You give it a push. At first it is barely bigger than your fist and it rolls slowly. But every turn picks up a little more snow, and each new layer makes the ball wider, so the next turn picks up even more. Halfway down it is the size of a football. By the bottom it is taller than you are. Nobody added snow by hand — the ball grew faster and faster simply because it was already big. That is compounding, and it is the closest thing investing has to a superpower.
The formal version sounds duller than it is: compounding is when the returns on your money start earning returns of their own. But hold on to the snowball, because the picture is doing the heavy lifting. Everything else in this article is just that hill, described in numbers.
Money that makes money, which makes money
Say you put £100 into something that grows 10% a year. After year one you have £110 — your original £100 plus £10 of growth. So far, nothing surprising.
Here is the twist. In year two, that 10% is not calculated on your original £100. It is calculated on the whole £110, because the £10 you earned is now part of the pot and gets to grow too. So you earn £11, not £10, and finish the year on £121. In year three you earn even more, because now you are growing £121. The gains themselves have started producing gains.
That small shift — earning a return on your returns — is the entire idea. Each year your money grows on top of a slightly bigger base, and a bigger base means a bigger gain, which makes the base bigger still. It is a loop that feeds itself, exactly like the snowball gathering snow because it already has snow.
Simple growth versus compound growth
It helps to see what compounding is not. Imagine two £1,000 pots, both growing at 10% a year, but with one difference.
- Simple growth pays 10% only on the original £1,000. That is a flat £100 every single year, forever. Steady, but it never speeds up.
- Compound growth pays 10% on the original £1,000 plus everything it has already earned. So the yearly gain is £100, then £110, then £121, then more — climbing every year.
In the early years the two pots look almost identical, and that is the trap that makes people give up too soon. But watch what the gap does over time:
| Years | Simple growth | Compound growth |
|---|---|---|
| Start | £1,000 | £1,000 |
| 5 years | £1,500 | £1,611 |
| 10 years | £2,000 | £2,594 |
| 25 years | £3,500 | £10,835 |
| 40 years | £5,000 | £45,259 |
After five years the compound pot is barely ahead. After forty it has left the simple pot nine times over — from the same starting money and the same 10%. The only extra ingredient was time. This is why a graph of compound growth curves upward instead of running in a straight line: the longer it goes, the steeper it climbs.
Why time matters more than the amount
Most people assume the way to get rich from investing is to start with a lot of money. Compounding says something stranger and more hopeful: what matters most is not how much you start with, but how long you leave it.
Take two savers. Alex starts at 18, puts away a modest amount, and then stops adding anything at 28 — just ten years of saving. Sam waits until 30 to begin, saves twice as much as Alex each month, and keeps going all the way to 60. On paper Sam pours in far more money. Yet because Alex's early pot had a dozen extra years to compound before Sam even started, the two often finish surprisingly close — and in many versions of this classic example, the early starter actually ends up ahead.
The lesson is almost unfair, and it is worth saying plainly: the best day to start was as early as possible, and the second best day is today. Every year you wait is not just a year of missed growth — it is a missed year at the front of the queue, the layer of snow that every future layer would have been built on.
The quiet enemy: compounding in reverse
The same loop that builds wealth can also drain it, and beginners rarely get warned about this. Two things compound against you.
The first is fees and costs. A charge of 1% a year sounds tiny, but it is skimmed off the top of your growing pot every year, so it compounds too — and over decades a “small” annual fee can quietly swallow a large slice of your final total. When grown-ups fuss over keeping investment costs low, this is why.
The second is selling too early. Every time you cash out a good holding, you take it off the hill and stop it rolling. The snowball only grows while it keeps moving. This is the deeper reason behind the case we make in why holding beats trading for most beginners: constant buying and selling doesn't just risk bad timing, it repeatedly interrupts the very process that was working in your favour.
Where dividends fit in
Compounding gets an extra engine when a company pays you along the way. As we explain in what a dividend actually is, some shares hand you a slice of the profit as cash. If you spend that cash, fine — but if you use it to buy a few more shares, those new shares then earn their own dividends, which buy yet more shares. You have plugged the payout straight back into the snowball. Professionals call this reinvesting dividends, and over long periods it has done a remarkable share of the total growth of the stock market — often more than the rise in prices alone.
What this means inside the challenge
Be honest about the timescale first. The Student Investor Challenge runs across a school year, and real compounding is a story told in decades, not months. You will not watch your virtual £100,000 quietly snowball into millions before the semi-finals — that is not how a few months work, and any game that promised it would be lying.
So why does it matter here at all? Because the challenge is really training a set of instincts, and compounding shapes one of the most valuable ones. It teaches you to see a healthy, growing holding as something worth leaving alone to keep working, rather than something to flip the moment it ticks up. That patience — the willingness to let good decisions run — is the same instinct that separates strong long-term investors from busy, anxious ones. It also connects to how you build the whole thing in the first place, which is the subject of what a portfolio really is: a collection meant to grow together over time, not a pile you churn every week.
The one thing to remember
Compounding is just growth earning more growth, repeated. There is no clever trick hidden inside it and no shortcut that makes it hurry. It asks for only two things — a reasonable return and a lot of patience — and it rewards the second far more than most people expect. Start early, keep costs low, let the good things run, and let time roll the snowball down the hill. That is not exciting advice. It is simply the advice that works.
FAQ
What is compounding in simple terms?
It is when the growth on your money starts earning growth of its own. Rather than only your original amount earning a return, last year's returns are added on and earn a return too — so the pot grows on top of a steadily bigger base and speeds up the longer you leave it.
What is the difference between simple and compound growth?
Simple growth pays a return only on your original amount, so it rises in a straight line. Compound growth pays a return on your original amount plus everything it has already earned, so the line curves upward and gets steeper over the years.
Why does starting early matter so much?
Because compounding needs time even more than it needs money. The extra years let each round of growth pile on top of the last, so someone who starts small but early often overtakes someone who starts with far more but leaves it fewer years.
Does compounding work in the Student Investor Challenge?
A single school year is too short to show decades of compounding. But the habit the game builds — letting strong holdings keep growing instead of cashing out early — is exactly the mindset that compounding rewards over a lifetime.
Learn it by playing it
Build a virtual £100,000 portfolio and watch patience do its quiet work.
See how it works